PhilHealth Voluntary Contribution: How Much in 2026?
When I first declared ₱8,000 as my monthly income on my PMRF, I’d done the math myself: 5% of ₱8,000 is ₱400. The teller corrected me before I’d even finished writing the amount. Anything below ₱10,000 still gets charged at the ₱10,000 rate. Every article I’d read said “5% of income” and left out the part that actually mattered.
On this page
Quick Answer
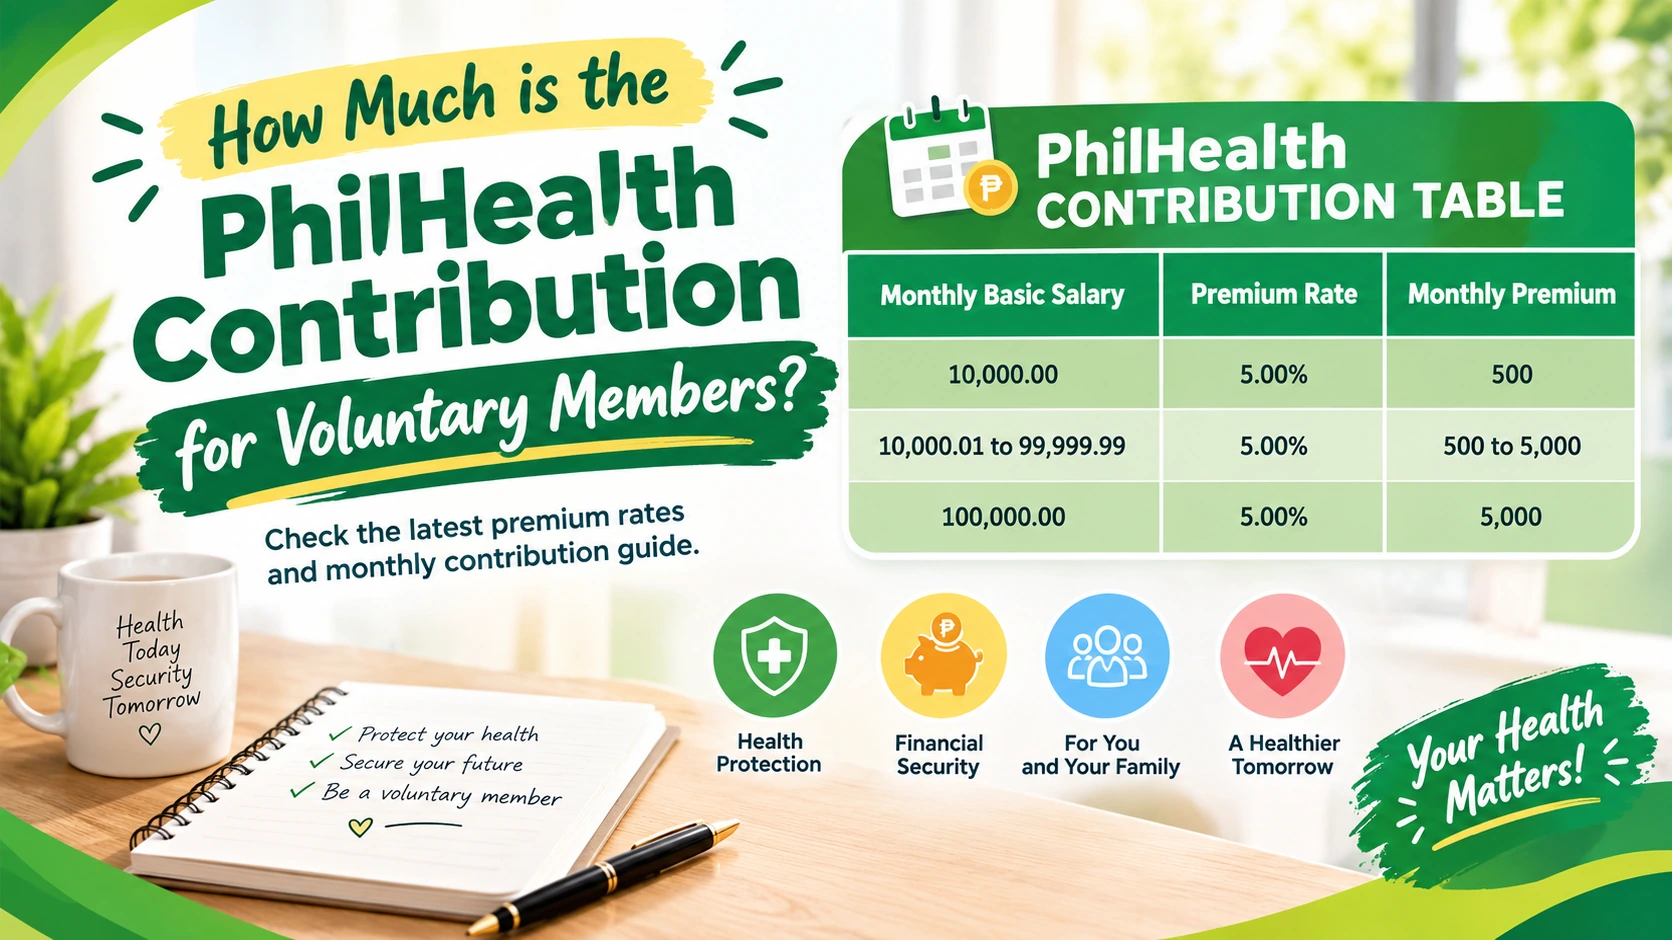
PhilHealth contribution for voluntary members in 2026 is 5% of your declared monthly income, with a ₱10,000 income floor and a ₱100,000 ceiling. That works out to a minimum of ₱500 a month and a maximum of ₱5,000, and unlike employed members, you pay the full amount yourself since there’s no employer to split it with. This rate has held steady since 2024, per the schedule set under PhilHealth Circular No. 2019-0009 implementing the Universal Health Care Act.
Full Contribution Table by Income
Here’s exactly what 5% works out to at different declared income levels, floored at ₱10,000 and capped at ₱100,000.
| Declared Monthly Income | Monthly Contribution (5%) |
|---|---|
| ₱10,000 and below | ₱500 (minimum) |
| ₱15,000 | ₱750 |
| ₱20,000 | ₱1,000 |
| ₱25,000 | ₱1,250 |
| ₱30,000 | ₱1,500 |
| ₱40,000 | ₱2,000 |
| ₱50,000 | ₱2,500 |
| ₱75,000 | ₱3,750 |
| ₱100,000 and above | ₱5,000 (maximum) |
Prefer not to do the math by hand? Our contribution calculator gives you the exact figure for any income you enter.
What “Voluntary” Actually Means
“Voluntary member” isn’t a distinct official category under PhilHealth’s current Informal Economy framework, it’s the term many people, and even some PMRF guides, still use for what PhilHealth generally classifies as a Self-Earning Individual within the Informal Economy membership type. PhilHealth’s own current member classification page doesn’t list “Voluntary” as one of its named subgroups, though older PMRF versions and several active guides still use it as a checkbox label.
In practice, this naming difference doesn’t change your contribution. Whether a branch or a guide calls you “Voluntary,” “Self-Employed,” or “Self-Earning Individual,” the computation is identical: 5% of your declared income, paid in full by you.
Minimum and Maximum Contribution
The lowest possible PhilHealth contribution is ₱500 a month, charged to anyone declaring ₱10,000 or less in monthly income. The highest is ₱5,000 a month, charged once declared income reaches ₱100,000. Nothing you declare below the floor or above the ceiling changes either number.
How to Compute Your Exact Amount
- Write down your average monthly income. Use a realistic average if it fluctuates month to month.
- Compare it to ₱10,000 and ₱100,000. Below ₱10,000, use ₱10,000. Above ₱100,000, use ₱100,000.
- Multiply by 5%. That’s your monthly contribution.
For example, ₱35,000 declared income × 5% comes to ₱1,750 a month. See our full contribution guide for how this compares across every membership category, not just voluntary.
How to Pay as a Voluntary Member
You can pay online through the Member Portal linked to GCash, Maya, or your bank’s bills-payment feature, using your PIN as the reference number. Over-the- counter options include accredited banks, payment centers, and any PhilHealth Express outlet or LHIO branch.
Whichever channel you use, double-check your PIN is entered correctly before paying, a misrouted payment under the wrong PIN is far more annoying to fix than it is to prevent.
Payment Schedule and Deadlines
Per PhilHealth’s official registration guidance for Informal Economy members, you can pay monthly, quarterly, semi-annually, or annually.
| Schedule | Deadline |
|---|---|
| Monthly | Last working day of the month being paid for |
| Quarterly | Last working day of the quarter being paid for |
| Semi-annual | Last working day of the first quarter of the semester being paid for |
| Annual | Last working day of the first quarter of the year being paid for |
Paying further ahead doesn’t change your rate for the covered months, it just means fewer trips to pay later.
What Happens If You Miss a Payment
Missing a payment doesn’t cancel your membership the way a lapsed private insurance policy might. Your PIN and record stay intact, you simply fall behind on your contribution count. The real risk shows up at claim time: PhilHealth’s standard eligibility rule generally requires at least three months of contributions within the six months immediately before a confinement, so a long enough gap can mean a claim gets denied even though your membership itself is still active.
Catching up is straightforward, pay what you’ve missed and resume your regular schedule. There’s no separate penalty fee for late voluntary contributions, just the eligibility gap while you’re behind.
Mistakes to Avoid
- Forgetting the income floor. Declaring under ₱10,000 doesn’t lower your contribution below ₱500.
- Paying under the wrong PIN. Always confirm your PIN before submitting payment through any channel.
- Assuming a missed month is a minor issue. It can affect your eligibility right when you might need to file a claim.
- Declaring an income you can’t reasonably support if asked. Keep a simple record of how you arrived at your declared figure.
Frequently Asked Questions
What is the lowest PhilHealth contribution?
₱500 a month, charged to anyone declaring ₱10,000 or less in monthly income under the 5% rate and income floor.
How to pay PhilHealth for voluntary members?
Pay online through the Member Portal using GCash, Maya, or bank bills payment, or over the counter at accredited banks, payment centers, or any PhilHealth Express outlet, using your PIN as reference.
What is the minimum monthly contribution to PhilHealth in 2026?
₱500, based on the 5% rate applied to the ₱10,000 income floor. This has held steady since 2024.
What does “voluntary” mean in PhilHealth?
It’s the commonly used term for members who pay their own premium without an employer, now generally classified under PhilHealth’s Informal Economy category rather than as its own distinct official type.
Is the contribution rate different for voluntary members compared to employed members?
The rate itself is the same 5%, but voluntary members pay the full amount themselves, while employed members split it 50/50 with their employer.
Can I pay more than the minimum to get better PhilHealth benefits?
No. Case rates and benefit amounts are fixed regardless of how much you contribute above the minimum, as long as you meet the standard eligibility requirements.
Not sure if “voluntary” is actually your category?
Our membership category guide and Informal Economy guide cover how PhilHealth classifies members today.